


News Center
News Center
Brief Analysis of Chemical Fiber Industry Operation in the First Half of 2022
Release time:
2022-08-29
In the first half of the year, unexpected factors such as the rebound of domestic epidemics and international geopolitical conflicts had an impact on China's economic operation, and the risks and challenges facing development continued. In this context, crude oil prices fluctuate sharply, downstream demand continues to be sluggish, and the overall production and operation situation of the chemical fiber industry is severe. However, under the support of a series of national "steady growth" policy measures, the main operating indicators of the textile industry have shown pressure to rebound. It is expected that in the second half of the year, with the further implementation of policy measures, it will bring more benefits to the smooth operation and recovery of the industry. Positive impact.
In the first half of the year, unexpected factors such as the rebound of domestic epidemics and international geopolitical conflicts had an impact on China's economic operation, and the risks and challenges facing development continued. In this context, crude oil prices fluctuate sharply, downstream demand continues to be sluggish, and the overall production and operation situation of the chemical fiber industry is severe. However, under the support of a series of national "steady growth" policy measures, the main operating indicators of the textile industry have shown pressure to rebound. It is expected that in the second half of the year, with the further implementation of policy measures, it will bring more benefits to the smooth operation and recovery of the industry. Positive impact.
First, the basic situation of the operation of the industry.
(I) Production and marketing
In the first half of the year, the overall operating load of the chemical fiber industry was weaker than that of the same period last year, especially after mid-March, there was a significant decline, and since then the overall low-load operation has been maintained. According to the data of the National Bureau of statistics, the year-on-year growth rate of chemical fiber production has generally slowed down since this year (Figure 1). From January to June, the output of chemical fiber was 33.67 million tons, achieving a weak positive growth year-on-year, and the growth rate from January to June was slightly higher than that from January to May.
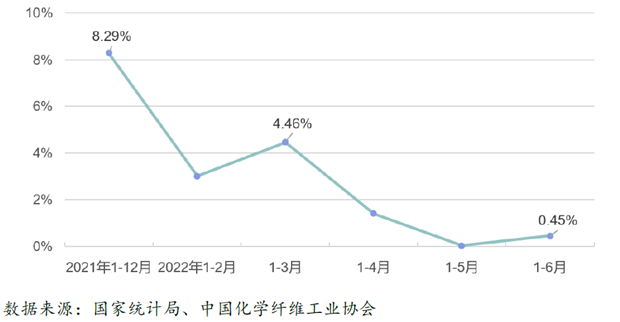
Figure 1 Change in year-on-year growth rate of chemical fiber production in 2022
In the first half of the year, the terminal bomb, weaving by the order and high inventory pressure, the start load is weak, the demand for chemical fiber continued to be sluggish, so the chemical fiber industry production and sales pressure is greater, the overall inventory is at a high level, polyester staple fiber and viscose staple fiber inventory is relatively low (Figure 2).
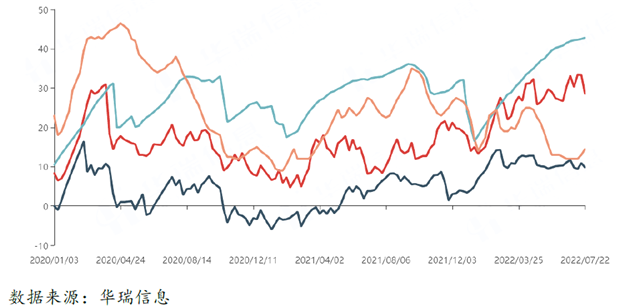
Figure 2 Inventory of major chemical fiber products since 2020
(II) market price
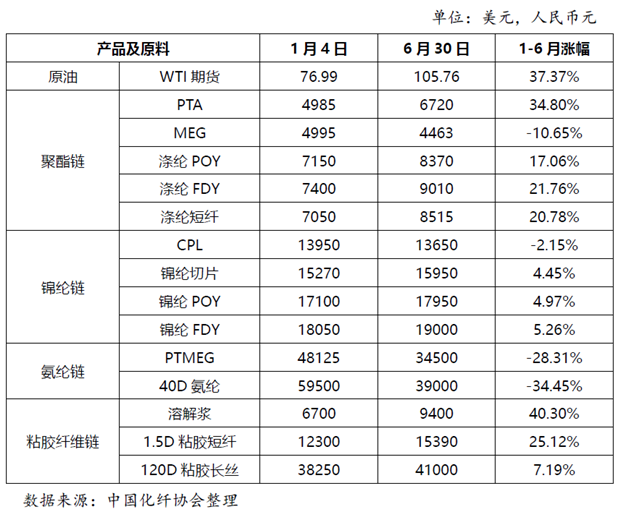
Since 2022, crude oil prices have generally remained high and fluctuated sharply. WTI futures exceeded US $120/barrel twice in early March and early June, and then showed a downward trend, falling to US $106/barrel at the end of June and further falling to around US $94/barrel at the end of July, down more than 20% from the June high. The chemical fiber market represented by polyester also showed a high and large fluctuation trend (Figure 3). On the one hand, although the high price of crude oil has formed a certain support for the price of chemical fiber, the downstream demand continues to be sluggish, and it is difficult for chemical fiber companies to smoothly transmit the rising costs downward. Therefore, the price increase of chemical fiber products is generally less than that of upstream raw materials (Table 1), and profit margins are squeezed. On the other hand, the sharp fluctuations in the prices of raw materials and chemical fiber products have increased the difficulty of market judgment and production and management.
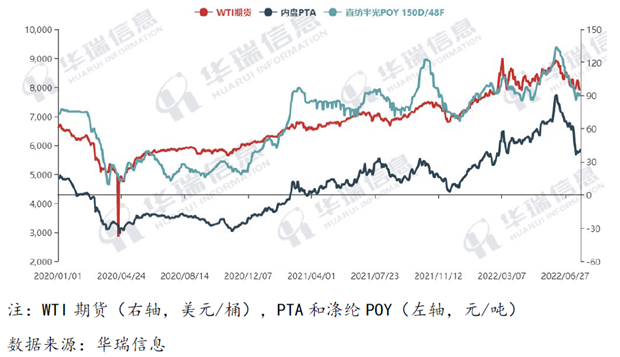
Figure 3 Price trends of international oil prices, PTA and polyester POY since 2020
Table 1 Price changes of main products and raw materials of chemical fiber in the first half of the year
(III) Import and Export
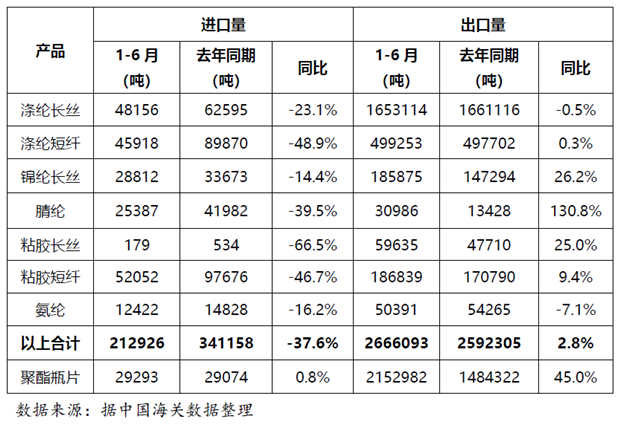
According to China Customs statistics (Table 2), the total import volume of major chemical fiber products from January to June decreased by 37.6 year-on-year. On the one hand, it reflects the weakening of domestic market demand, and more importantly, domestic chemical fiber products have been able to meet downstream demand in terms of variety and quality. Under the difficult situation, chemical fiber exports still achieved positive growth. From January to June, the total export volume of major products increased by 2.8 year-on-year, reflecting the increase in international market demand and the improvement of the competitiveness of my country's chemical fiber products. In particular, it is worth mentioning that the export performance of polyester bottles in the past two years is bright, with the export volume increasing by 36% year-on-year in 2021 and 45% year-on-year in January-June 2022.
Table 2 Import and export of main chemical fiber products in the first half of 2022
(iv) End markets
From the point of view of terminal consumption, the domestic demand market by the epidemic distribution impact once fluctuated, since May, with the domestic epidemic has been effectively controlled, the national "promotion fee" policy is effective, textile domestic consumption is returning to good. According to data from the National Bureau of Statistics, from January to June, the retail sales of clothing, shoes, hats, and knitwear products of units above the national quota decreased by 6.5 year-on-year, but the rate of decline narrowed by 1.6 percentage points from January to May this year; the growth of online retail channels was relatively stable. In the first half of the year, the national online clothing retail sales increased by 2.4 year-on-year, up 1.5 percentage points from the first quarter of this year, reversing the negative growth trend since April.
The textile external demand market has grown steadily. According to China Customs data, China's textile and clothing exports totaled US $156.49 billion billion from January to June, an increase of 11.7 percent over the same period last year. Supported by the increase in export prices, the export amount reached the highest level in the same period over the years. Among the export products, the export value of textiles was 76.32 billion US dollars, a year-on-year increase of 11.3; the export value of clothing was 80.17 billion US dollars, a year-on-year increase of 12%. In the export market, the textile supply chain of Southeast Asia and other countries has basically resumed normal operation this year, driving my country's exports of its yarn, fabric and other industrial chain supporting products to achieve good growth. From January to June, my country exported a total of 27.71 billion billion U.S. dollars of textiles and clothing to ASEAN. An increase of 23.3 percent, of which the growth rate of yarn and fabric exports reached 29.9 percent and 24.6 percent respectively; china's exports to (RCEP) member countries of the Regional Comprehensive Economic Partnership Agreement reached 45.57 billion billion US dollars, an increase of 13.7 percent over the same period last year, indicating that the effective implementation of RCEP is conducive to the stability and improvement of the export environment.
(V) economic benefits
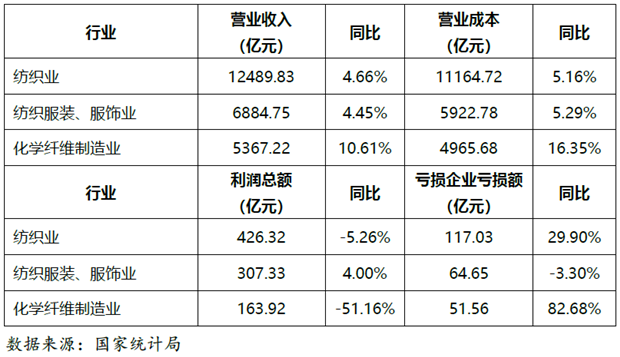
In the first half of the year, the profit margin of the chemical fiber industry was compressed, and due to the high base in 2021, the profit decreased significantly year-on-year. According to data from the National Bureau of Statistics (Table 3), the operating income of the chemical fiber industry from January to June 2022 was 536.7 billion yuan, an increase of 10.61 percent over the same period last year; operating costs increased by 16.35 percent over the same period last year, 5.74 percentage points higher than the increase in operating income; total profits reached 16.4 billion billion yuan, a decrease of 51.16 percent over the same period last year; the industry lost 33.54 percent, and the losses of loss-making enterprises increased by 82.68 percent, it was 88.32 percentage points lower than January-May.
Table 3 Economic benefits of chemical fiber and related industries in January-June
(VI) investment in fixed assets
According to the National Bureau of Statistics, fixed asset investment in the chemical fiber industry increased by 31.9 year-on-year in January-June, basically the same as the annual growth rate in 2021 (Figure 4), reflecting to some extent that enterprises have sufficient confidence in future development.
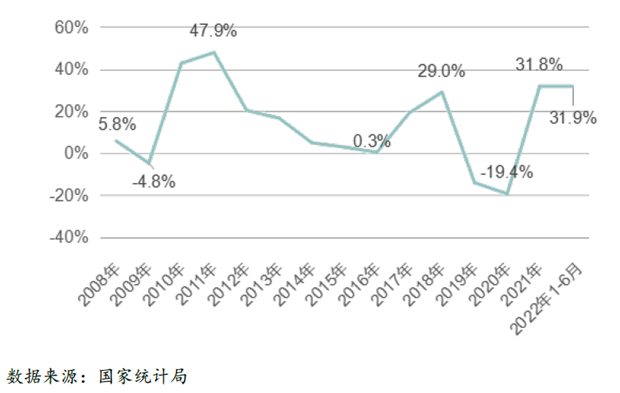
Figure 4 Changes in the growth rate of fixed asset investment in the chemical fiber industry since 2008
Second, the second half of the industry operation trend forecast.
From the cost side, the crude oil market in the second half of the year is mainly affected by geopolitical conflicts and the Fed's interest rate hikes. The uncertainty is still strong but the probability of being short is increasing. It is expected that it may still show a wide range of shocks, and the price center may be lower. In the first half of the year, the possibility of a sharp decline is not ruled out. The decline in crude oil prices will reduce the pressure on raw material costs and energy costs for chemical fiber companies, but companies need to control inventories and be wary of inventory depreciation affecting their book efficiency.
From the consumer side, the textile industry has shown signs of gradual improvement, with the basis for recovery. In the second half of the year, it is expected that as the country's series of solid economic stabilization policies continue to show results, my country's macro economy is expected to further stabilize and rebound, providing a solid foundation for the improvement of the domestic demand market and the smooth production and demand cycle. Under the expectation, the domestic textile market is expected to achieve a weak recovery; while the external demand market is facing competition from Southeast Asia and other countries.
Generally speaking, it is expected that the operating pressure of the chemical fiber industry will still be great in the second half of the year, and the industry will continue to carry a heavy load. It is expected that the operating income of the chemical fiber industry is still expected to show a growth trend year-on-year, and the overall profit level is expected to improve compared with the first half of the year.
Industry enterprises must strengthen their confidence, believe that the difficulties are temporary, and believe that the industrial foundation and industrial advantages formed by my country's chemical fiber and textile industries over the years are still outstanding. In the face of uncertainty, to do certain things, it is recommended that enterprises prevent risks and practice internal skills, actively implement the overall requirements and key tasks of the ''Guiding Opinions on the High-quality Development of the Chemical Fiber Industry'', and move towards high-end, intelligent, and green High-quality development is moving forward, and the 20th National Congress of the Party is held with practical actions!
(Source: China Chemical Fiber Industry Association)
More information



Follow us
Hello, what can we do for you?
Copyright © Xiantao Dexing Plastic Products Co., Ltd / Xiantao Dexing Health Technology Co., Ltd | Powered by:300.cn
SAF Coolest v1.3.1.2 设置面板 FZUSD-ZSNG-OSSQE-ZWE
无数据提示
Sorry, the current column is being updated, please look forward to it!
You can view other columns or returnHome Page