


News Center
News Center
January-November 2021 China Garment Industry Economic Operation Briefing
Release time:
2022-01-21
In November, China's clothing production recovered steadily, domestic sales continued to improve, exports maintained rapid growth, corporate profit growth accelerated significantly, the industry as a whole continued the development trend of steady recovery, showing the industry transformation and innovation continued to deepen, digital empowerment accelerated, the rise of domestic goods to promote brand upgrading and other development characteristics. However, the external environment facing the industry is becoming more complex and severe, the epidemic and other factors on the domestic and foreign market demand continued to recover a certain impact, raw material prices remain high, the pressure of rising enterprise costs is still large, the foundation of the stable and healthy operation of the industry still needs to be further consolidated.
In November, China's clothing production recovered steadily, domestic sales continued to improve, exports maintained rapid growth, corporate profit growth accelerated significantly, the industry as a whole continued the development trend of steady recovery, showing the industry transformation and innovation continued to deepen, digital empowerment accelerated, the rise of domestic goods to promote brand upgrading and other development characteristics. However, the external environment facing the industry is becoming more complex and severe, the epidemic and other factors on the domestic and foreign market demand continued to recover a certain impact, raw material prices remain high, the pressure of rising enterprise costs is still large, the foundation of the stable and healthy operation of the industry still needs to be further consolidated.
1 Economic Operation of Clothing Industry from January to November 2021
Clothing production stable recovery
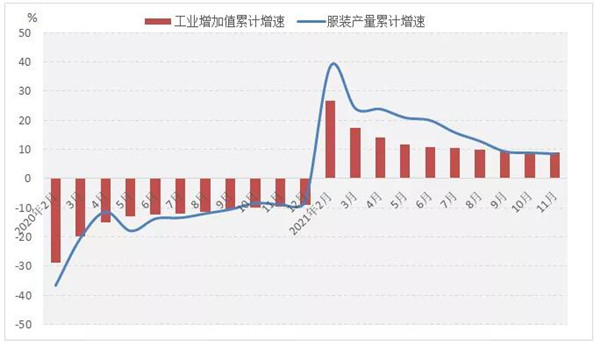
In November, driven by factors such as the rebound in market demand, the promotion of the two festivals and the active stocking of overseas Christmas season, clothing production recovered steadily and the growth rate returned to normal. According to data from the National Bureau of Statistics, from January to November 2021, the industrial added value of enterprises above designated size in my country's garment industry increased by 8.9 year-on-year, and the growth rate was 18.5 percentage points higher than the same period last year, and the two-year average decline was 0.8 (based on the corresponding same period in 2019, calculated using the geometric average method, the same below); enterprises above designated size completed 21.294 billion pieces of clothing, an increase of 8.53, the growth rate was 17.28 percentage points higher than the same period last year, and the two-year average decline was 0.5 percent, equivalent to a return to 99 percent of apparel production in the same period in 2019. From the perspective of the output of the main categories of clothing, benefiting from exports, the production of knitted clothing maintained a rapid growth, with an increase of 12.37 per cent, with an average growth of 2.6 per cent in two years, while the output of woven clothing increased by 3.18 per cent year-on-year, with an average decline of 4.6 per cent in two years.
Figure 1 Production growth rate of the clothing industry from January to November 2021
Source: National Bureau of Statistics
Steady improvement in domestic market
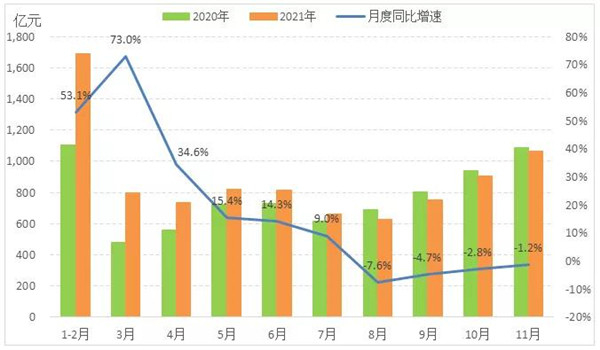
In November, driven by the "Double Eleven" shopping festival, clothing sales in the domestic market improved steadily, the decline in retail sales of clothing products per unit above the monthly limit continued to narrow, and online consumer demand continued to release. According to the National Bureau of Statistics, from January to November 2021, China's retail sales of clothing goods per unit above the limit totaled 890.61 billion yuan, an increase of 16.4 percent over the same period last year and an average increase of 2.7 percent in two years; in November, retail sales of clothing goods per unit above the limit fell 1.2 percent year-on-year, a decrease of 1.6 percentage points narrower than the previous month. In the same period, online retail sales of clothing goods increased by 11.1 year-on-year, an increase of 5.2 percentage points over the same period last year, and an average increase of 8.5 in two years.
Figure 2 Monthly retail sales of clothing goods in units above the quota
Source: National Bureau of Statistics
export maintained rapid growth
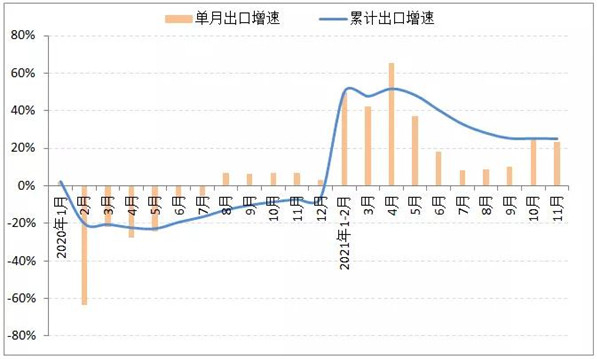
In November, driven by the increasing demand in the international market and the promotion and preparation of goods for Christmas season, China's clothing exports continued to grow significantly, with a monthly export growth of 23.2 per cent compared with the same period last year. According to China's customs data, from January to November 2021, China completed a total of 154.35 billion billion U.S. dollars in exports of clothing and clothing accessories, an increase of 25.1 percent year-on-year, an average two-year growth of 7.7 percent, and an average two-year growth rate of 0.7 percentage points higher than that of January-October. Among them, the export of knitted garments and clothing accessories increased strongly, with the export value of 78.214 billion US dollars, up 39.88 percent year-on-year, with an average growth of 9.5 percent in two years; the export of woven garments and clothing accessories maintained a steady growth, with the amount of 63.382 billion US dollars, up 12.28 percent year-on-year, with an average growth of 2.57 percent in two years.
Fig. 3 Export of Clothing and Clothing Accessories
Data source: China Customs
The growth rate of China's clothing exports to the United States has slowed down from last month, and exports to the Belt and Road have maintained rapid growth. According to China's customs data, from January to November, China's clothing exports to the United States were 36.143 billion billion US dollars, up 37.71 percent year-on-year, 3.35 percentage points slower than that from January to October. Among them, China's clothing exports to the United States increased only 9.88 percent year-on-year in November. Clothing exports to the European Union, Japan and ASEAN increased by 21.97 percent, 8.48 percent and 26.34 percent respectively, the above four countries/regions together drove the growth of my country's clothing exports by 15.17 percentage points. During the same period, China's clothing exports to countries and regions along the Belt and Road increased by 28.62 percent year-on-year, with an average growth of 8.04 percent in two years, of which clothing exports to Kyrgyzstan, Saudi Arabia and the United Arab Emirates increased by 218.04 percent, 48.54 percent and 71.22 percent respectively.
Continuous recovery of operation quality
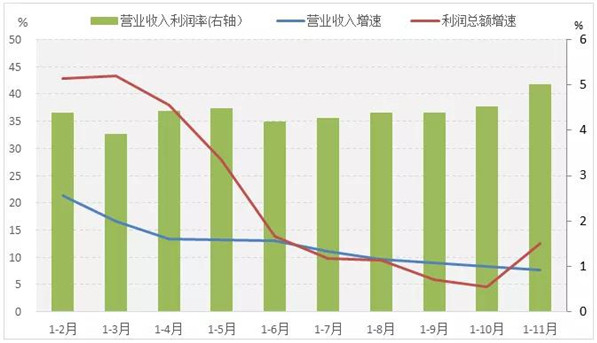
Profit growth accelerated significantly. According to the data of the National Bureau of Statistics, from January to November 2021, there were 12659 enterprises above the scale of China's clothing industry (annual main business income of 20 million yuan and above), with an operating income of 1330.307 billion yuan, an increase of 7.73 percent over the same period last year, an increase of 20.08 percentage points over the same period last year. The total profit was 66.691 billion billion yuan, an increase of 12.64 percent over the same period last year, an increase of 33.43 percentage points over January-October, and 8.07 percentage points, among them, the total profit in November increased by 63.1. Compared with the same period in 2019, the average two-year decline in operating income and total profit of the apparel industry was 2.8 and 5.5, respectively, 0.1 and 3.8 percentage points lower than in January-October.
Figure 4 The main benefit indicators of the clothing industry from January to November 2021.
Source: National Bureau of Statistics
The operational efficiency of the enterprise has improved and the profitability has increased. From January to November, the loss area of enterprises above Designated Size in the clothing industry was 20.65, 4.22 percentage points lower than that of the same period of last year; the proportion of three fees was 8.94, down 0.03 percentage points from the same period of last year; the turnover rate of total assets, finished products and accounts receivable were 1.25 times/year, 12.68 times/year and 7.39 times/year respectively, 4.01, 1.29 and 2.34% respectively; the operating income margin was 5.01 percent, up 0.22 percentage points from a year earlier.
Investment scale rebounded slightly
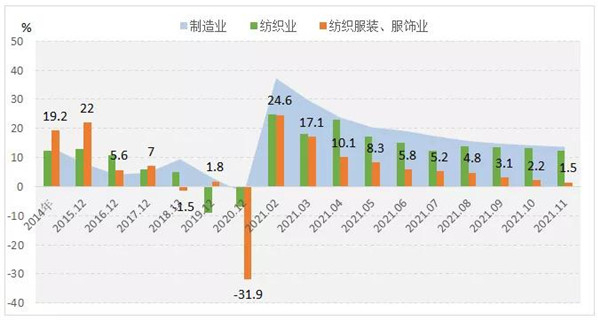
According to the National Bureau of Statistics, from January to November 2021, the completion of fixed asset investment in China's garment industry increased by 1.5 year-on-year, an increase of 31.3 percentage points over the same period last year, still lower than the overall level of the textile industry and manufacturing industry 10.9 and 12.2 percentage points. Compared with the same period in 2019, fixed asset investment in the apparel industry fell by an average of 15.6 percent over the two years, 0.8 percentage points lower than in January-October, and has not yet returned to pre-epidemic levels.
Figure 5 Growth rate of fixed asset investment in the apparel industry
Source: National Bureau of Statistics
2 main development characteristics of garment industry
Industry continues to pick up
In November, driven by the continuous recovery of the domestic economy, the winter cold wave and the "Double Eleven" promotion and other factors, my country's domestic clothing market has recovered significantly, and the demand for the clothing industry has gradually released. Winter is the traditional peak season for clothing sales. With the onset of the cold wave, most parts of China have entered the freezing mode. Consumers' demand for warm clothing such as down jackets, cashmere sweaters, and thermal underwear has increased significantly, which has driven the turnover of related products. At the same time, driven by the "Double Eleven" shopping festival, online and offline commodity consumption promotion activities have also promoted the positive improvement of sales in the clothing industry. In addition, with the approach of the Beijing Winter Olympics, the residents' enthusiasm for sports was ignited, which led to the consumption of outdoor sports clothing. In this context, garment enterprises also actively grasp the needs of consumers and create innovative products with both functionality and fashion.
Digital Empowerment Accelerated
At present, digital transformation is driving profound changes in production methods, business models and enterprise organization, and the epidemic has spawned the rapid development of new business forms and new models, accelerating the pace of digitalization of enterprises. Clothing enterprises are actively promoting digital transformation. The manufacturing end upgrades the supply chain system through intelligent transformation, single-piece flow and flexible production. The design end drives the demand and growth of consumers through innovative trend product design. The consumer end uses the establishment of a consumer data platform to open up online and offline sales data and accurately locate the target population. Through digital transformation, clothing enterprises such as Taiping Bird and Golis continue to empower channels, marketing and brand operations, improve operational efficiency and promote sustained growth in performance.
At the same time, as the application of virtual reality, artificial intelligence, blockchain, big data, 5G, wearable devices and other technologies matures, the meta-universe, which is considered to be the future of the digital economy, is booming. Clothing enterprises have also started to explore the Yuan universe one after another. Goliath has launched the brand virtual character Elisa, Hailan House and Semir Apparel have successively applied for registration of the relevant trademarks of the Yuan universe.
The rise of domestic products boosts brand upgrade
With the enhancement of consumers' national self-confidence and the rise of the younger generation of consumer groups, more and more domestic brands have entered the public's vision with a new attitude by excavating the traditional culture and history of the brand, integrating new technologies and new trends. A new wave of national style. This year's "Double Eleven" data shows that among the brands with a turnover of more than 100 million yuan, nearly 50% of domestic brands, an increase of 17% year-on-year. Among the Top10 brands with a year-on-year growth rate of turnover, 8 are domestic brands. The rapid growth of the overall sales of domestic brands reflects that the new generation of consumers pay more attention to the culture and heritage of products. According to the changes in the concepts of Chinese consumers, many domestic brands continue to innovate and create products with more personality and better quality. For example, Bosideng pioneered trench coat down jacket, which fully combines the styles and advantages of the two classic categories of trench coat and down jacket to meet the wearing needs of business occasions. Li Ning launched a new independent senior sports fashion brand LI-NING 1990 to broaden the product boundary and lay out the high-end market.
(Source: China Garment Association)
Previous article
Previous article
In the fourth quarter of 2021, the textile industry boom rose.
More information



Follow us
Hello, what can we do for you?
Copyright © Xiantao Dexing Plastic Products Co., Ltd / Xiantao Dexing Health Technology Co., Ltd | Powered by:300.cn
SAF Coolest v1.3.1.2 设置面板 FZUSD-ZSNG-OSSQE-ZWE
无数据提示
Sorry, the current column is being updated, please look forward to it!
You can view other columns or returnHome Page